A private sale leaves no trail. No broker files a form. No title company mails a copy to the IRS. Cash or a wire transfer changes hands. A handshake closes the deal, and both people walk away thinking the story ends there. For most people, it does end there, at least on paper. That gap between what the law requires and what actually gets reported is where this piece lives.
I want to walk you through two versions of that gap, because they teach two very different lessons. One is about a sale that should have been reported and wasn’t. The other is about a sale that got reported the wrong way entirely, if it got reported at all.
The Sale With No Paper Trail
Recently I wrote about a watch sale I overheard at a party. A seller there was quietly creating a capital gain he probably never planned to report. Nobody sends the IRS a form when you sell a personal watch to a private buyer. Stocks generate a 1099 from the brokerage. Real estate generates paperwork from the title company. A private sale of a personal item generates nothing but a memory, and maybe a receipt if he happens to have kept one.
That silence creates a strange kind of confidence. People assume that because nobody is watching, nothing is technically happening. The law disagrees. The gain still exists, and it stays taxable whether or not a form ever gets filed. Reporting depends entirely on the seller choosing to do it, and plenty of sellers never choose that.
Where the Paper Trail Sneaks Back In
The absence of a 1099 does not mean total invisibility forever. A cash payment over $10,000 triggers a Form 8300 filing on the dealer’s end, naming the seller directly. Large bank deposits can trigger their own reporting requirements. Someone already carrying an outstanding IRS balance draws extra scrutiny too, since collections activity tends to invite a closer look at overall finances.
So the honest read is this. Most private sales stay invisible in practice. Some do not, and the ones that resurface later tend to look worse than an honest mistake would have. An unreported gain that surfaces on its own can start to resemble concealment, even when nobody intended it that way.
The Guy in the Driveway
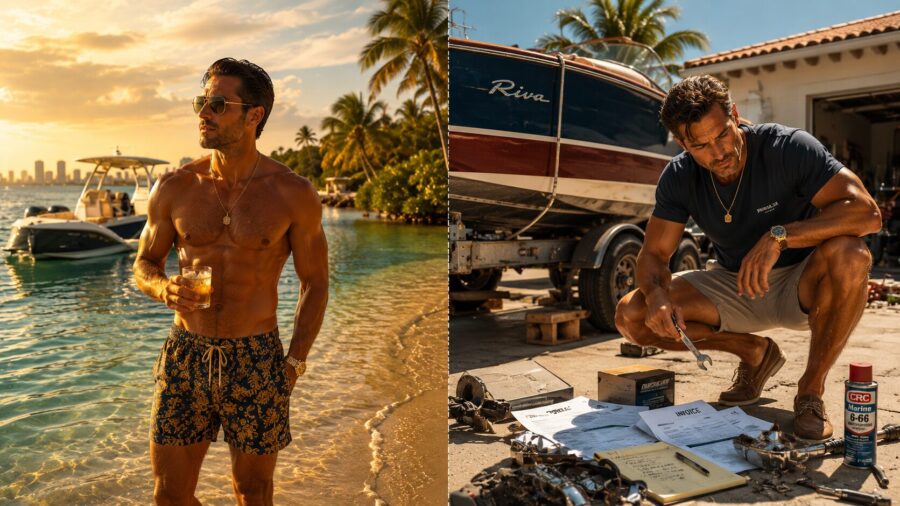
Now picture a different guy entirely, someone I will call Danny because half of Miami seems to know a version of him. Danny is more Miami than Mr. 305 himself, gold chain catching the sun, a cold drink always within reach, and a build that says beach mornings matter more than desk hours. At the sandbar, he is the one everyone already knows, trading stories like old friends with people he met an hour ago, never short on company and never the first to leave. Danny fixes air conditioners for a living. He works big installation jobs in concentrated bursts, then takes long stretches off between projects. That downtime goes to the water, and a good chunk of that lifestyle gets funded by buying boats.
Danny finds them on Facebook Marketplace (and other online sources) or through word of mouth. People in his circle already know he can restore something half sunk into something that turns heads at the sandbar. A typical “buy” might run $30,000, with another $12,000 going into parts and plenty of his own labor on top. He uses it for a season and enjoys it properly. Then he sells it for a solid profit and starts again. More than one boat usually sits in his driveway at once, one finished and for sale, one halfway done, one still waiting its turn.
Danny almost certainly treats every one of these sales as a private transaction, same as the watch seller from last week. He is wrong, and wrong in a much bigger way than simply skipping a form.
This Was Never a Capital Gain to Begin With
Here is the piece most people miss entirely. The tax code excludes certain property from counting as a capital asset in the first place. Under IRC §1221(a)(1), that exclusion applies to anything held primarily for resale in the ordinary course of a trade or business. Courts built this rule around real estate flippers, but the same logic applies to boats, cars, furniture, or anything else bought and resold on a repeating cycle.
The IRS and the courts weigh a cluster of factors here. Frequency and continuity of sales carry the most weight. Improvements made, marketing activity, and how close together the buying and selling happen all matter too. Danny checks nearly every box on that list. He buys repeatedly, improves each boat substantially with his own labor and money. Then, he sells on a pattern tight enough to call a business rather than a hobby.
That distinction changes everything about how his profit gets taxed.
The Bill Nobody Sees Coming
If Danny counts as a dealer rather than an occasional seller, his profit stops being a capital gain sitting quietly on Schedule D. It becomes ordinary business income reported on Schedule C, taxed at rates up to 37 percent depending on his total income. On top of that, he owes 15.3 percent in self-employment tax on his net earnings. That figure covers Social Security and Medicare, according to current IRS guidance. Neither layer shows up if you assume, the way Danny probably does, that this is just a guy flipping boats for beer money.
Run the math on one flip. He buys for $30,000, spends $12,000 on parts, and sells for $58,000. That leaves a $16,000 profit before his own labor even enters the picture. As a capital gain, that number would land somewhere in the 15 to 20 percent range depending on his income. As business income, it stacks on top of his HVAC earnings and gets taxed at his marginal rate instead. Then it loses another 15.3 percent off the top for self-employment tax. The gap between those two outcomes on a single boat can run into the thousands, and Danny is not flipping just one boat a year.
The Upside He’s Also Missing
Dealer status is not purely bad news, and this is the part that always surprises people. Proper classification as a business changes the cost side too. Parts and rehab costs flow through as real, deductible expenses instead of sitting invisible outside the picture. A qualified business income deduction becomes available. At a certain profit level, electing S-corp treatment can meaningfully cut the self-employment tax bite, something I laid out in detail in LLC vs S-Corp.
Danny is likely leaving real money on the table by staying invisible, not just risking a bill down the road. Structured properly, this side hustle could fund a SEP-IRA and shelter income through legitimate deductions. It could build toward something that looks like an actual business instead of a hobby that happens to generate cash. Most people never make that call because they never realize there is a call to make.
The Asymmetry That Ties Both Stories Together
Here is where the watch seller and Danny end up in the same place, even though they got there completely differently. The tax code treats personal property gains and losses asymmetrically. Suppose the watch seller had sold at a loss instead of a gain. He could not have deducted a dime of it, because losses on personal-use property never qualify as deductible. Gains stay taxable. Losses on personal items simply disappear.
Danny’s situation flips that rule entirely, and this detail deserves real attention. If his boat flipping counts as a genuine trade or business, a loss on a bad flip becomes a real, deductible business loss. That loss works the same as any other cost of doing business. The government wants a cut of every gain either way. Whether it grants any relief on the losses depends entirely on how your activity gets classified, not on fairness and definitely not on what feels intuitive to the seller.
That is the real lesson underneath both of these stories. Classification decides almost everything. Almost nobody thinks about classification until it is too late to choose it on their own terms.
This piece may have left you wondering whether an occasional sale owes more than you assumed. This one should leave you wondering something bigger. If you run any kind of repeating side activity, the government may already see a business where you only see a hobby with good margins.
Welcome to the New Age of Accounting. Let’s begin.
P.S. If you found this article helpful, you’ll love my new book S-Corp Mastery: How Smart Business Owners Maximize Tax Savings & Build a Lasting Legacy. It’s now live and available in a sleek, easy-to-read PDF version. Grab your copy here

Chris is the Managing Partner at Weston Tax Associates, a best-selling author, and a renowned tax strategist. With over 20 years of expertise in tax and corporate finance, he simplifies complex tax concepts into actionable strategies that drive business growth. Originally from Sweden, he now lives in Florida with his wife and two sons.